The Gap Between Two Front Doors: What Bridging Loans Really Cost When You Buy Before You Sell
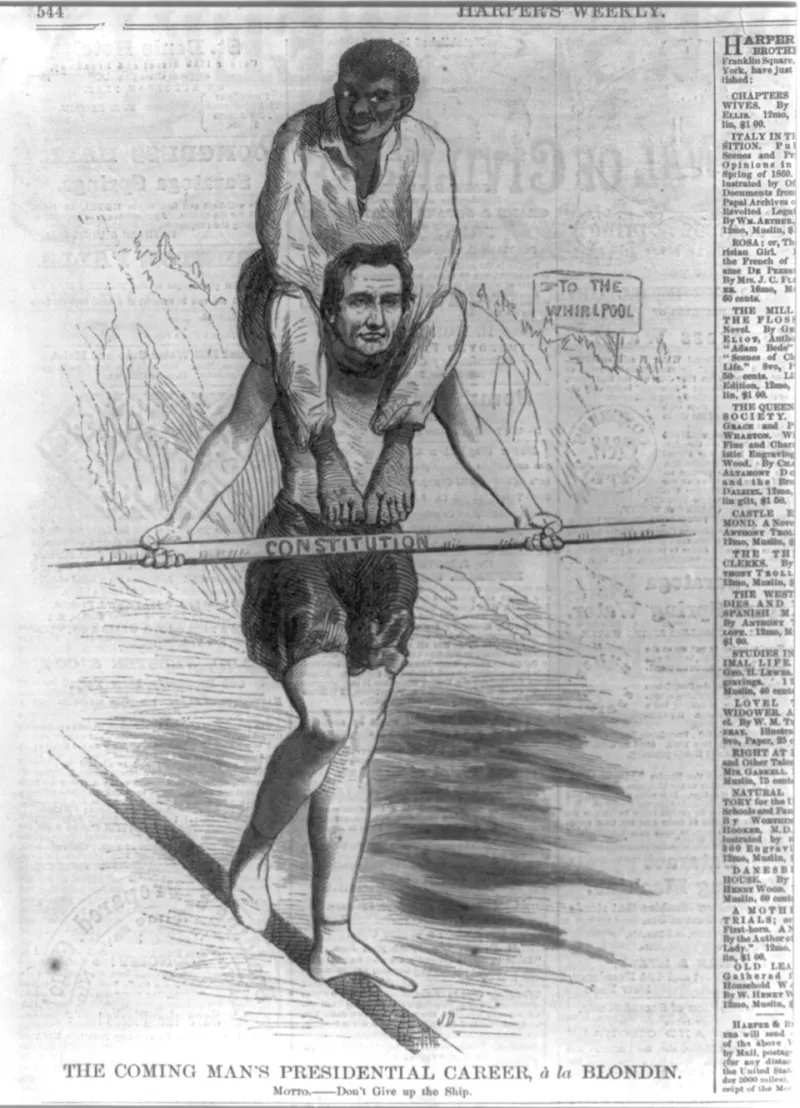
Photo: Miscellaneous Items in High Demand, PPOC, Library of Congress, Public domain, via Wikimedia Commons
There's a moment every mover knows. Your house has been listed for weeks, viewings have been polite but underwhelming, and then — there it is. The right house, in the right street, at a price that won't come round again. The estate agent senses your hesitation and deploys the four most dangerous words in UK property: "You could always bridge."
Sometimes that's sensible advice. Often it's a shortcut to a very expensive few months. Let's walk the tightrope properly.
What a Bridging Loan Actually Is
A bridging loan is short-term secured borrowing designed to cover the gap between buying one property and selling another. You borrow against your current home (or the new one, or both), complete the purchase, then repay the loan when your sale finally goes through.
They come in two flavours. Closed bridging means you already have a fixed exit — exchange has happened on your sale, completion date confirmed. Open bridging means you're betting the sale lands sometime soon, with no guaranteed date. Open bridge, open risk.
The Interest Problem — And It Compounds
Bridging rates typically run between 0.5% and 1.5% per month. Not per year. Per month. And most lenders quote them monthly for a reason: it sounds gentler than the annual equivalent, which can hit 12–18%.
Worse, many loans are arranged so interest is retained upfront or rolled up monthly — meaning you pay interest on interest. Let's run the numbers on a £150,000 bridge at 0.95% per month, interest rolled up:
Three months: roughly £4,300 in interest. Painful but survivable if your sale completes on time.
Six months: around £8,800. Now add the arrangement fee (often 2%, so £3,000), valuation fees, legal fees on two transactions, and an exit fee of perhaps 1% on repayment. You're nudging £14,000 — nearly 10% of what you borrowed — for the privilege of owning two homes at once.
Twelve months: interest alone climbs past £18,000, and total costs can breach £25,000. If your sale falls through and relists, that's a decade of overpayments on a typical mortgage, burned in one anxious year.
Compare that to a chained sale — where you negotiate a longer completion or a seller who'll accept a delayed exchange — and suddenly "just bridge it" deserves a second look.
The Exit Strategy Is Everything
No reputable bridging lender will touch you without a credible exit. They want to know exactly how this loan gets repaid: the sale proceeds, a remortgage onto a standard deal, or — less commonly — an inheritance or bonus due at a known date.
If your exit is "the house will probably sell", expect scrutiny. Lenders will want evidence: realistic pricing against recent comparables, a decent marketing history, sometimes even a valuation down-valuation if they think you're optimistic. If your exit fails, they can repossess. This isn't a credit card with a stern letter attached.
When Bridging Genuinely Makes Sense
To be fair to the estate agents, there are moments when bridging earns its keep:
- You're in a chain and someone above you will pull out unless you can complete fast. Speed is bridging's superpower — funds can land in days, not the months a standard mortgage takes.
- You're buying at auction, where completion is due within 28 days and no high-street mortgage can move that quickly.
- Downsizing with family help in the mix — say parents are gifting equity from their sale to fund yours, and the timings don't quite line up.
- A doer-upper that lenders won't touch yet, which you'll renovate then refinance onto a normal mortgage.
In each case, the bridge is a tool with a defined job and a defined end date. The trouble starts when it becomes a hope with a roof on it.
Questions to Ask Before You Sign
- What's the all-in cost? Rate, arrangement fee, exit fee, admin fees, valuation, legal costs on both sides. Get it as one number.
- Is interest retained, rolled up, or paid monthly? Rolling up inflates the balance; retaining means you pay for the full term even if you repay early.
- What happens if I exceed the term? Some lenders extend; some trigger penalty rates. Know before you're in the hole.
- What's my plan B if the sale stalls? A price reduction threshold, a rental backup, a family fallback. Decide it now, not in month five.
- Have I asked about alternatives? A longer completion window, a sell-then-rent-then-buy strategy, or a homebuyer's certificate from your seller can all remove the need for a bridge entirely.
The View From the Ladder
Bridging loans exist because property doesn't run on tidy schedules. Used carefully — short term, low loan-to-value, with a sale genuinely close to completing — they're a legitimate rung, not a trapdoor.
But the wire is real, and the safety net is your own equity. Before you step out, run the twelve-month worst case on paper. If that number makes you wobble, it's information. Sometimes the bravest move on the ladder is waiting for the one you're standing on to sell first.